- Updated:
- Published:
The titans of iGaming: which brands dominate the Global gambling landscape?
Bet365 holds the global revenue lead, and three Philippine brands have climbed into the acquisition top eleven from outside the top 120.
Bovada led Blask’s global CEB ranking for January–August 2025. It now sits third, behind Bet365 and FanDuel.
The reordering at the top is the smaller story. Betano more than doubled its earning baseline on the strength of a single market, and Philippine operators now supply three of the eleven largest acquisition benchmarks in the world — even as their own regulator reports the segment they operate in shrinking by double digits. Geographic reach continues to explain very little about what a brand earns.
The rankings below compare the top iGaming brands from January–August 2026 with the same eight months of 2025, based on Blask data.
The revenue heavyweights: top brands by CEB
Competitive Earning Baseline (CEB) projects the revenue a brand should capture from its market position. The average is the baseline, while the minimum and maximum reflect different competitive scenarios.
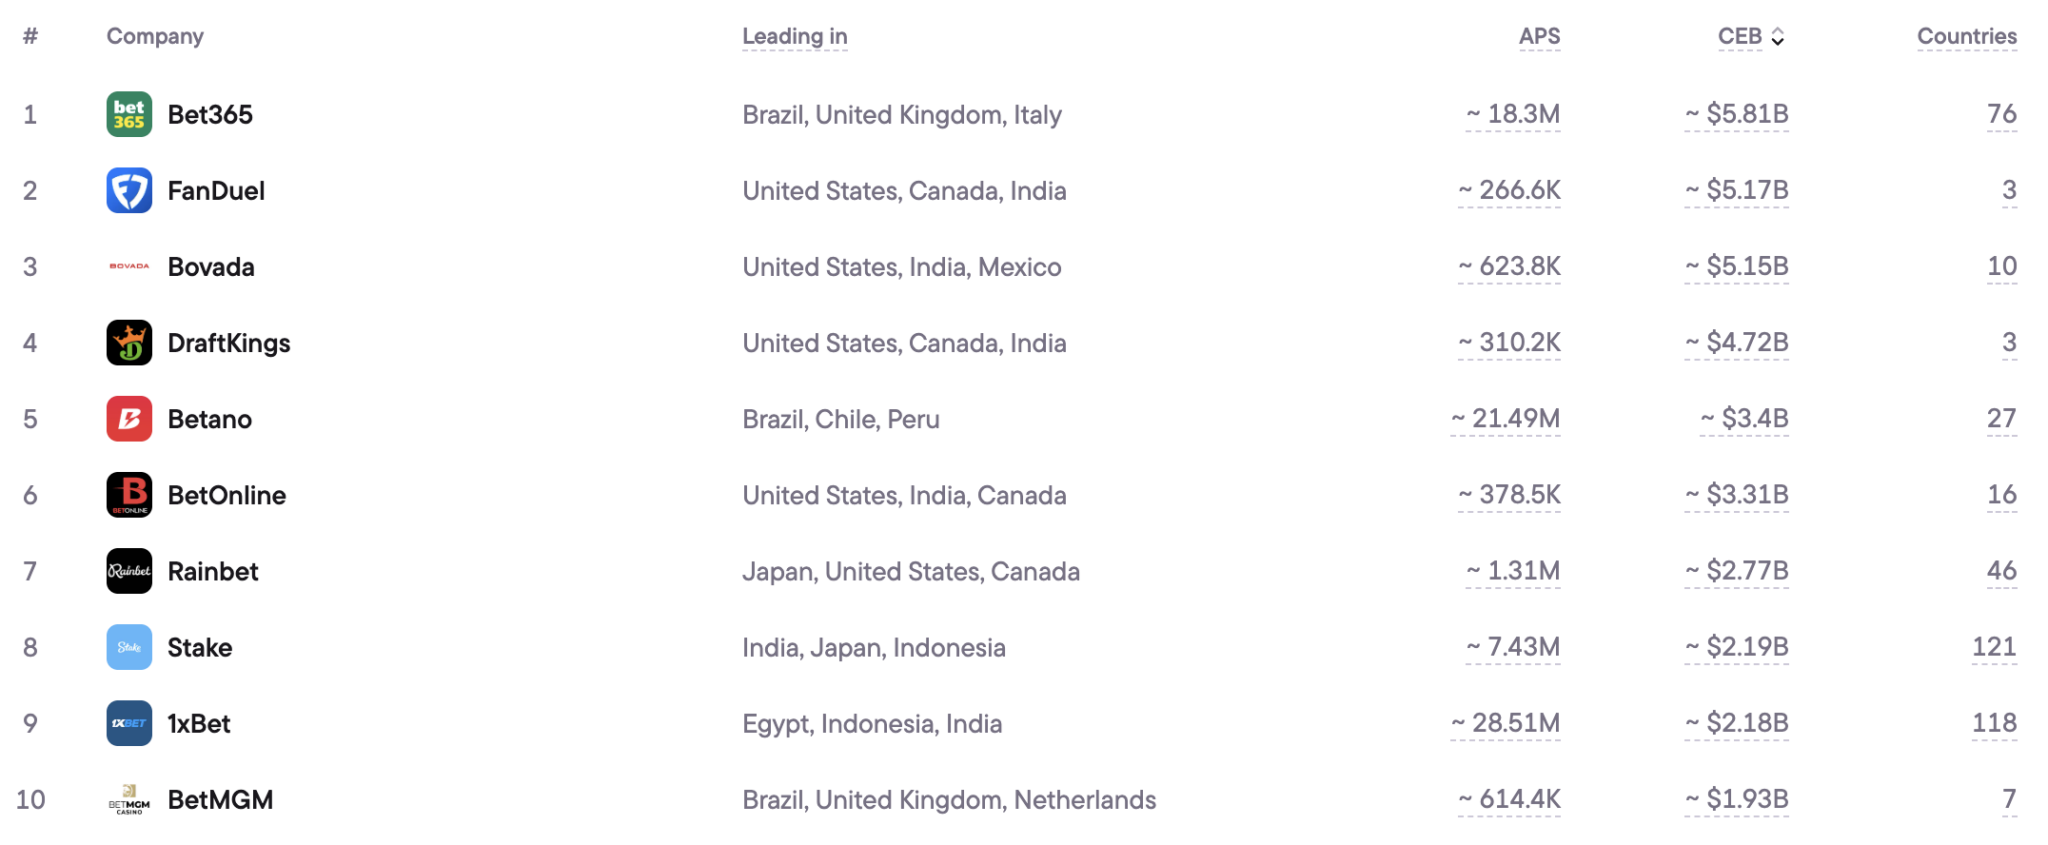
Top 10 brands by CEB, January–August 2026
| # | Brand | CEB average | CEB range | Jan–Aug 2025 | YoY | Rank in 2025 | Countries |
|---|---|---|---|---|---|---|---|
| 1 | Bet365 | $5.81B | $4.15B–$10.70B | $4.63B | +24.9% | 3 | 76 |
| 2 | FanDuel | $5.17B | $3.88B–$9.05B | $5.00B | +3.6% | 2 | 3 |
| 3 | Bovada | $5.15B | $2.58B–$12.88B | $5.43B | −5.1% | 1 | 10 |
| 4 | DraftKings | $4.72B | $3.54B–$8.25B | $4.55B | +3.6% | 4 | 3 |
| 5 | Betano | $3.40B | $2.42B–$6.35B | $1.51B | +125.4% | 10 | 27 |
| 6 | BetOnline | $3.31B | $1.66B–$8.28B | $2.83B | +17.0% | 5 | 16 |
| 7 | Rainbet | $2.77B | $1.38B–$6.90B | $146.8M | +1 779.7% | 202 | 46 |
| 8 | 1xBet | $2.19B | $1.15B–$5.27B | $2.21B | −1.2% | 6 | 121 |
| 9 | Stake | $2.18B | $1.10B–$5.36B | $2.13B | +1.4% | 7 | 118 |
| 10 | BetMGM | $1.93B | $1.45B–$3.39B | $2.08B | −7.0% | 8 | 7 |
Bet365 built its lead on one market. Brazil generated 48.0% of the brand’s global demand over the eight months, more than four times Britain’s contribution, and the brand’s monthly CEB stepped up 15.7% in January 2026 and stayed above $720M every month through July. Brazil has required federal authorization for fixed-odds betting since 1 January 2025, and the federal GGR levy rose to 13% from April 2026.
Betano took the same route further. Brazil supplied 70.8% of its global demand, enough to more than double its CEB and lift the brand from tenth to fifth. It finished the period $86.1M ahead of BetOnline, having trailed it for the whole of 2025. Kaizen Gaming made Betano Flamengo’s principal and front-of-shirt partner in August 2025.
The US-facing group barely moved. FanDuel and DraftKings each grew 3.6%, Bovada and BetMGM contracted, and BetOnline’s 17.0% gain was not enough to hold fifth once Betano passed it. Their seasonal curves still peak around the NFL playoffs and ease through the summer.
Rainbet remains the extreme case. Its CEB rose from $146.8M to $2.76B, but the gain came off a very low base and through one step change rather than a steady climb: monthly CEB jumped more than six-fold in October 2025 and has held near that plateau since. Rainbet became the first official sponsor of Kick’s Slots section in June 2026, extending a creator-led acquisition approach that had already lifted its demand. The US and Canada together supplied 34.5% of its global demand.
The sharpest move outside the top ten belongs to Superbet, which more than doubled its CEB to $1.15B and climbed from 41st to 18th. Blackstone and HPS refinanced the group with €1.3B in February 2025, earmarked for technology and Brazilian expansion, and Superbet holds one of Brazil’s definitive licenses.
The acquisition engine: top brands by APS
Acquisition Power Score (APS) estimates how many new players a brand should attract from its demand and market conditions. It is a benchmark rather than a reported first-time depositor count.
Top 10 brands by APS, January–August 2026
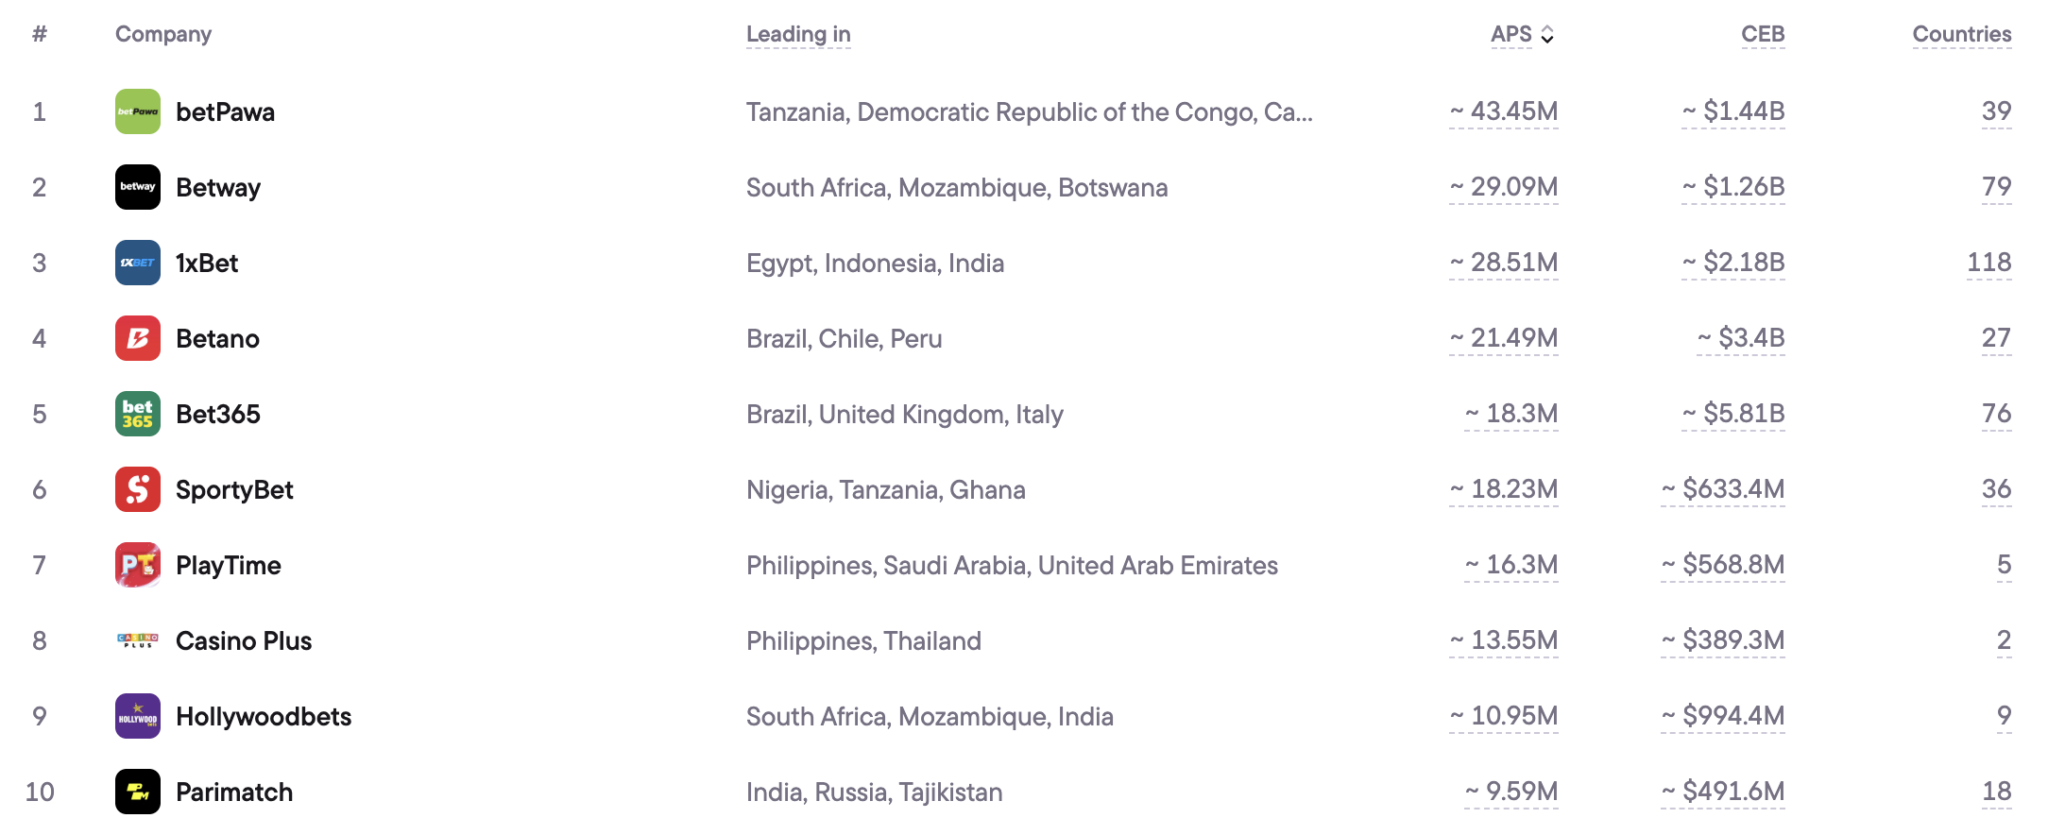
| # | Brand | APS average | APS range | Jan–Aug 2025 | YoY | Rank in 2025 | Countries |
|---|---|---|---|---|---|---|---|
| 1 | betPawa | 43.45M | 32.34M–76.79M | 34.12M | +27.4% | 1 | 37 |
| 2 | Betway | 29.09M | 21.71M–51.24M | 20.79M | +39.9% | 3 | 75 |
| 3 | 1xBet | 28.51M | 15.12M–68.67M | 26.17M | +9.0% | 2 | 114 |
| 4 | Betano | 21.49M | 15.39M–38.82M | 15.03M | +41.3% | 6 | 26 |
| 5 | SportyBet | 18.3M | 13.12M–33.55M | 10.26M | +77.6% | 7 | 35 |
| 6 | Bet365 | 18.23M | 12.42M–35.18M | 17.99M | +0.6% | 4 | 72 |
| 7 | PlayTime | 16.30M | 12.20M–28.62M | 1.32M | +1 133.3% | 122 | 5 |
| 8 | Casino Plus | 13.55M | 10.16M–23.72M | 1.07M | +1 168.2% | 147 | 2 |
| 9 | Hollywoodbets | 10.95M | 8.21M–19.18M | 8.36M | +31.1% | 10 | 9 |
| 10 | Parimatch | 9.59M | 4.93M–23.59M | 7.04M | +36.3% | 17 | 17 |
African brands still anchor the top of the acquisition ranking. betPawa held first place for a second year, Betway moved ahead of 1xBet, and SportyBet posted the fastest growth of any established African name, passing Bet365 for fifth. Nigeria supplied 52.5% of SportyBet’s global demand, with Tanzania and Ghana adding another 31.4%.
The structural change came from the Philippines. PlayTime and Casino Plus entered the top ten from outside the top 120, and Bingo Plus followed at eleventh, up from 180th, giving Philippine operators three places in the global top eleven. The Philippines accounts for all but a fraction of the demand behind each of them.
Their home market is contracting while those benchmarks rise. Philippine gross gaming revenue fell 20.33% year-over-year in the second quarter of 2026, with PAGCOR attributing the drop mainly to weaker electronic gaming — the segment these three brands sit in. Blask data shows the same split inside the brands themselves. All three reached their monthly CEB highs in December 2025, dropped sharply in January 2026, and are still running roughly half those peaks eight months later, while their monthly APS has climbed almost without interruption. Acquisition potential is building faster than the earning baseline beneath it.
Stake shows the mirror image. Its APS fell 53.1%, from 15.81M to 7.41M, dropping the brand from fifth to fifteenth, while its CEB edged up 1.4%. Stake is defending revenue potential on a weakening acquisition base.
The global footprint: presence across borders
Country coverage remains a poor guide to earning power. The brands with the widest maps span the revenue top ten and the bottom of the ranking alike.
The most global iGaming brands, August 2026
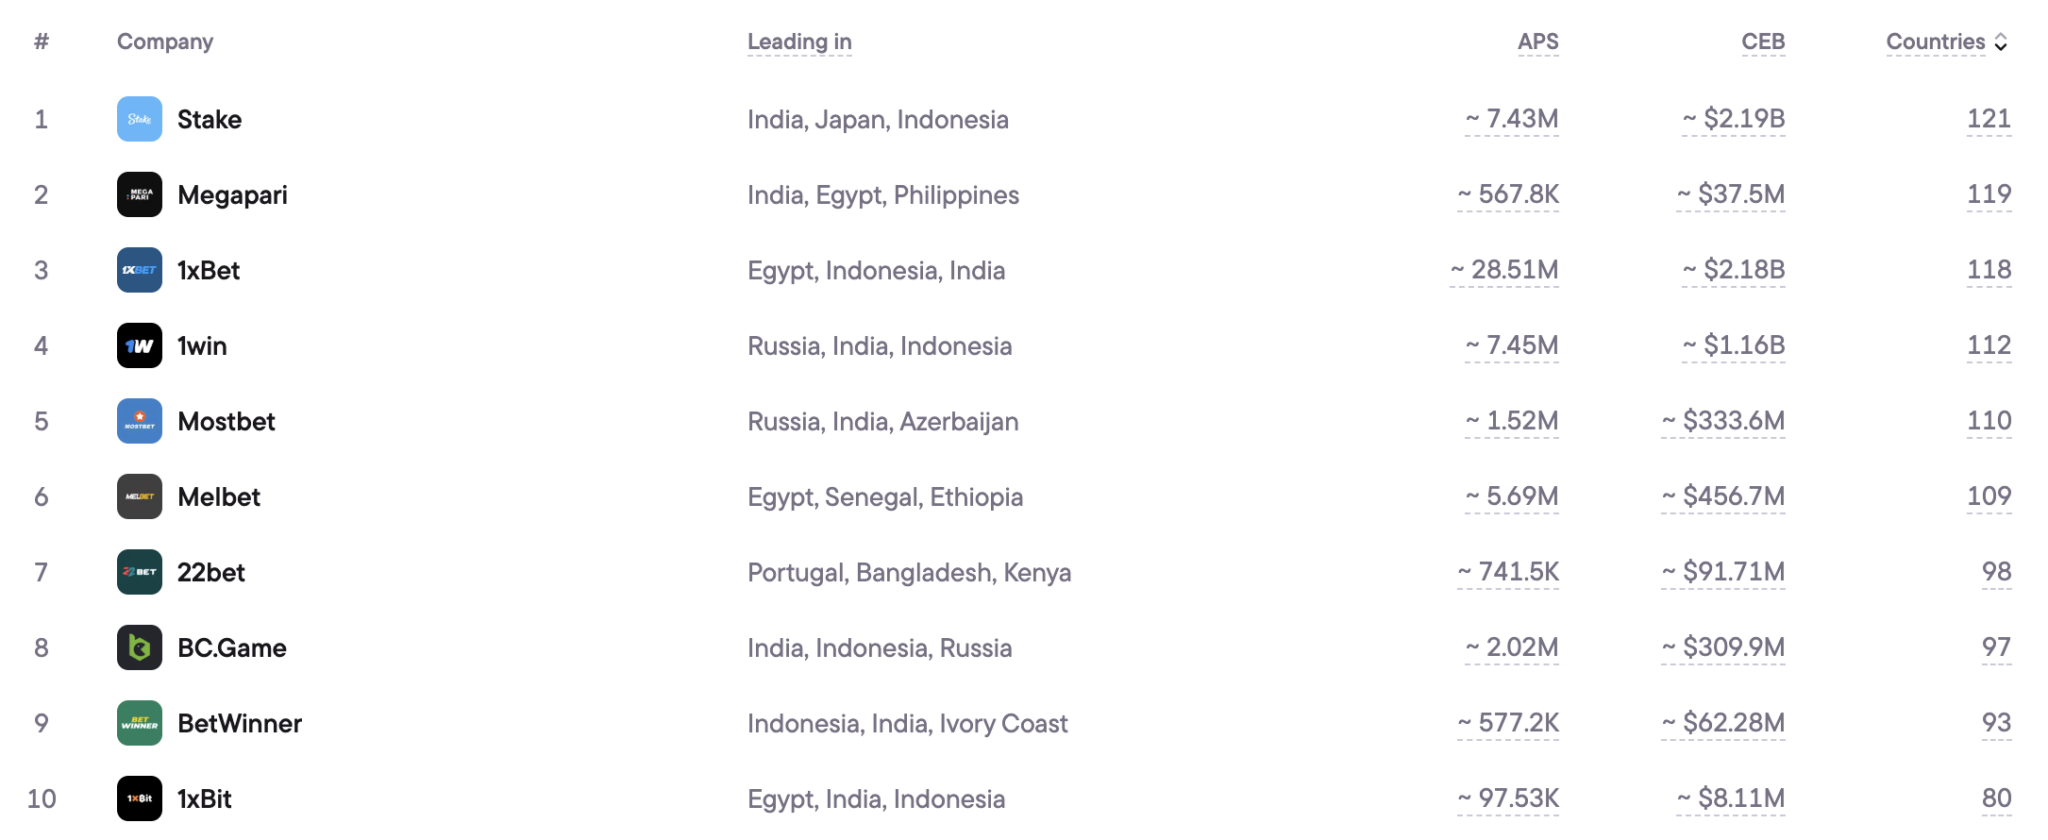
| # | Brand | Countries | CEB, Jan–Aug 2026 |
|---|---|---|---|
| 1 | Stake | 121 | $2.19B |
| 2 | Megapari | 119 | $37.5M |
| 3 | 1xBet | 118 | $2.18B |
| 4 | 1win | 112 | $1.16B |
| 5 | Mostbet | 110 | $333.6M |
| 6 | Melbet | 109 | $456.7M |
| 7 | 22bet | 98 | $91.6M |
| 8 | BC.Game | 97 | $309.8M |
| 9 | BetWinner | 93 | $62.3M |
| 10 | 1xBit | 80 | $8.1M |
1xBet and Megapari cover the same 115 countries, yet 1xBet’s CEB is 58 times larger. Lottomatica generated $1.28B from Italy alone, 34 times what Megapari produced across all 115. FanDuel and DraftKings each cleared $4.7B from three countries.
Stake and 1xBet are the only brands in this table that also hold a revenue top-ten place, and they arrive there differently. India and Canada together supplied 45.0% of Stake’s global demand, so the wide map collects a remainder while two countries decide close to half the outcome. 1xBet is the genuinely distributed case: Bangladesh is its largest market at 11.8%, and no other country reaches 8%.
Year-over-year: the 2025 vs. 2026 power shift
The revenue ranking proved stable. Nine of the ten brands in the 2025 top ten are still there; Rainbet is the only new entrant, and it displaced MyBookie. The movement happened inside the table rather than around it, with Bet365 passing Bovada and FanDuel for first and Betano climbing from tenth to fifth.
Acquisition turned over faster. Seven brands held a top-ten place, while Stake, 1win and 4RABET dropped out and PlayTime, Casino Plus and Parimatch replaced them. Rainbet’s climb from 202nd to seventh by CEB is the largest rank gain in either ranking, with PlayTime’s rise from 122nd to seventh by APS next.
Bottom line
Bet365 and Betano both converted Brazil’s regulated market into global position, and Brazil now decides roughly half of what the top-ranked revenue brand earns anywhere. Acquisition power keeps drifting toward Africa and, newly, the Philippines, where three brands are building record acquisition benchmarks inside a market whose reported revenue is falling. Whether that gap closes — and in which direction — is the thing to watch through the rest of 2026.