
A licence for sports betting does not by itself tell you where projected revenue will sit.
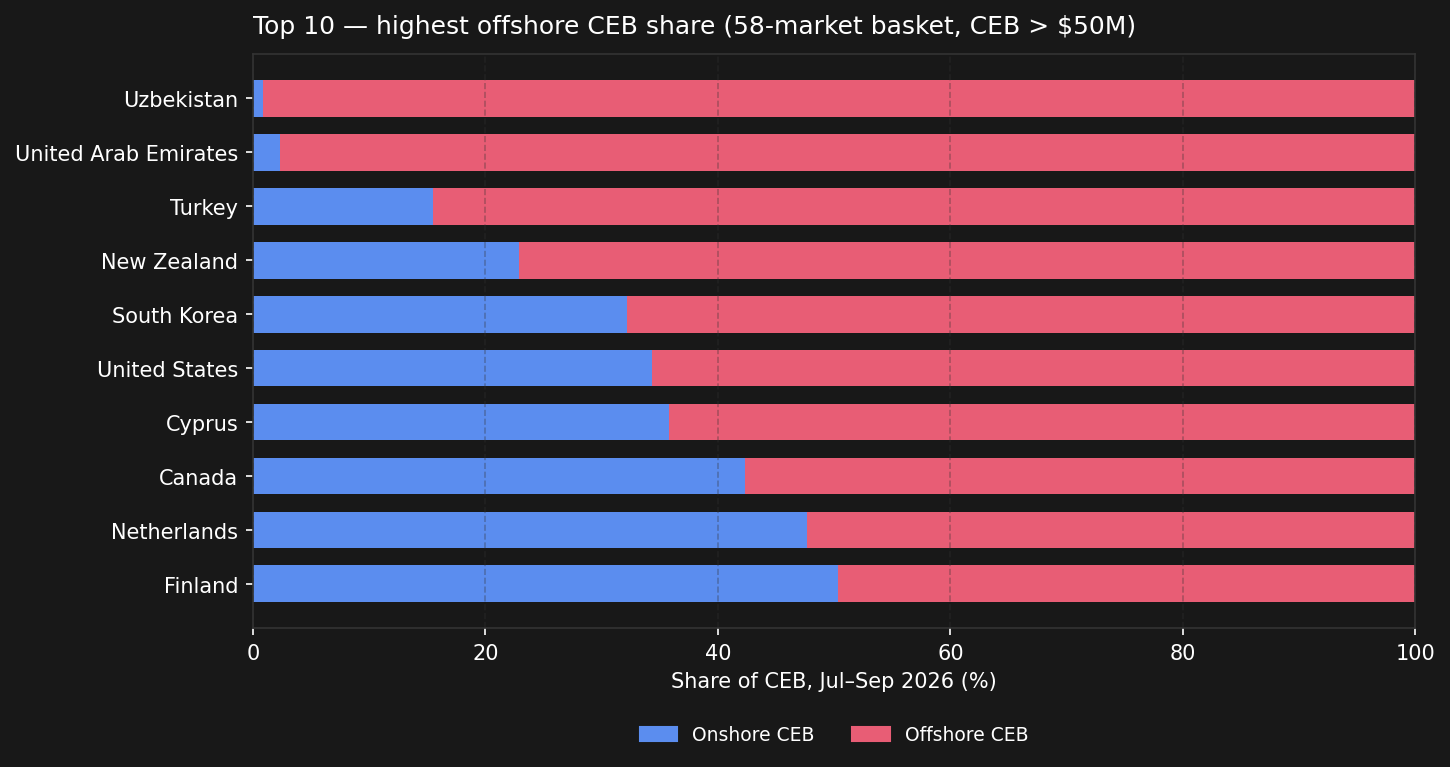
Blask’s Q3 2026 channelisation basket sorts large regulated-betting countries by the onshore share of CEB. The cut keeps 58 geos whose Jul–Sep CEB topped $50M and where online sports betting is legal — betting-only regimes and markets that also license online casino.
NAPP issued Uzbekistan’s first bookmaker licences in late July 2026 — too late for Q3 CEB to move. The UAE register still shows one internet gaming operator, Coin Technology Projects. Türkiye keeps 85% offshore CEB on $2.8B with casino banned; New Zealand is 77% offshore with sports via TAB but casino only entering via an October auction. The Netherlands sits near 52% offshore CEB, in line with KSA’s ~49% legal gross-gaming estimate for H1 2025.
The onshore top ten is mostly open Betting + Casino Europe and Latin America plus Nigeria: Peru and Nigeria above 98% onshore CEB, Brazil at 97% in the pre-shutdown quarter.
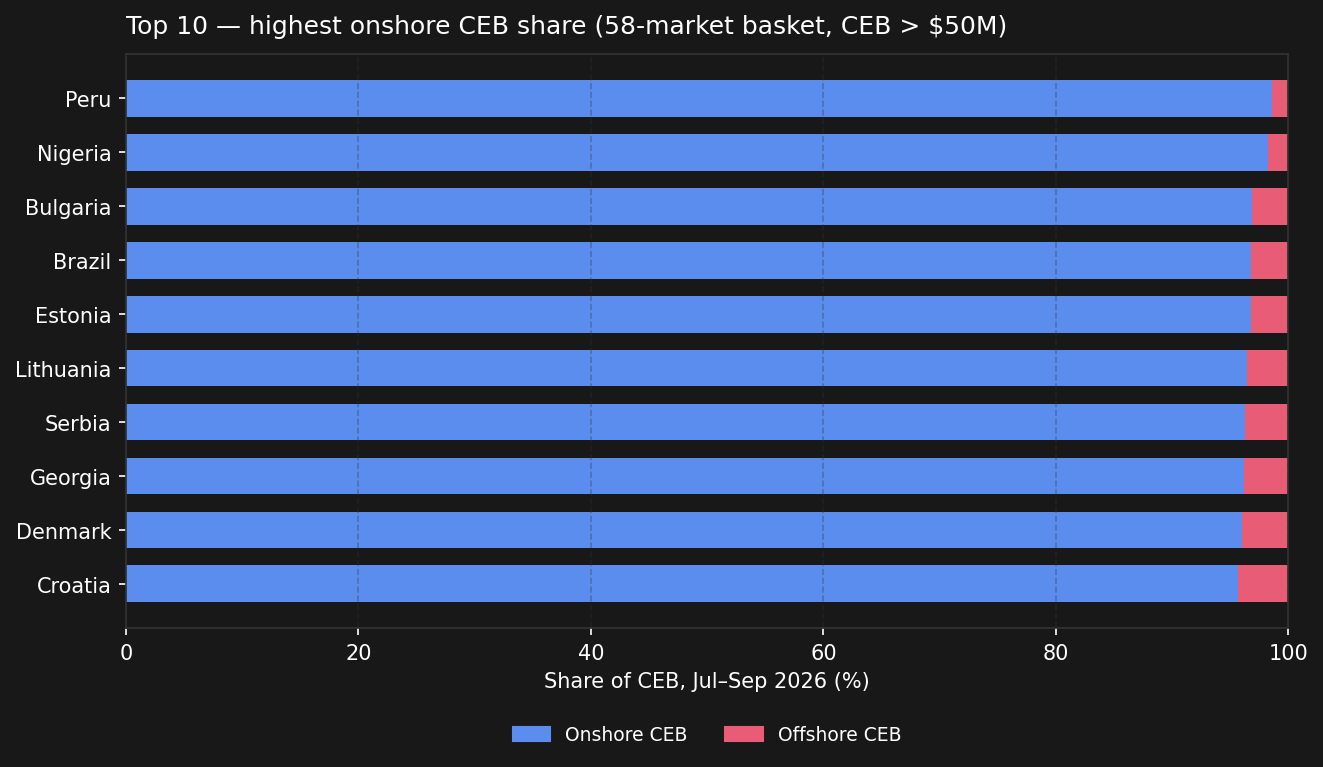
Channelisation here is time and product scope, not a yes/no on regulation. Fresh regimes stay offshore-heavy in Q3; mature open markets show what full CEB conversion can look like.