
The annual print is the licensed book, the same twelve months still have an offshore remainder.
On 17 September the UK Gambling Commission published Industry Statistics for April 2025 to March 2026. Licensed operators generated £17.5B in GGY, up 4.4% on the previous financial year. Excluding lotteries, the figure was £13.2B. Remote casino, betting and bingo — the closest licensed online line — rose 6.9% to £8.3B, while land-based sectors added 1.1% to £4.9B.
Those returns come from operators the Commission licenses. They stop at the regulated perimeter, and the year they describe ends in March 2026 — the last full financial year before Remote Gaming Duty rose to 40% in April.
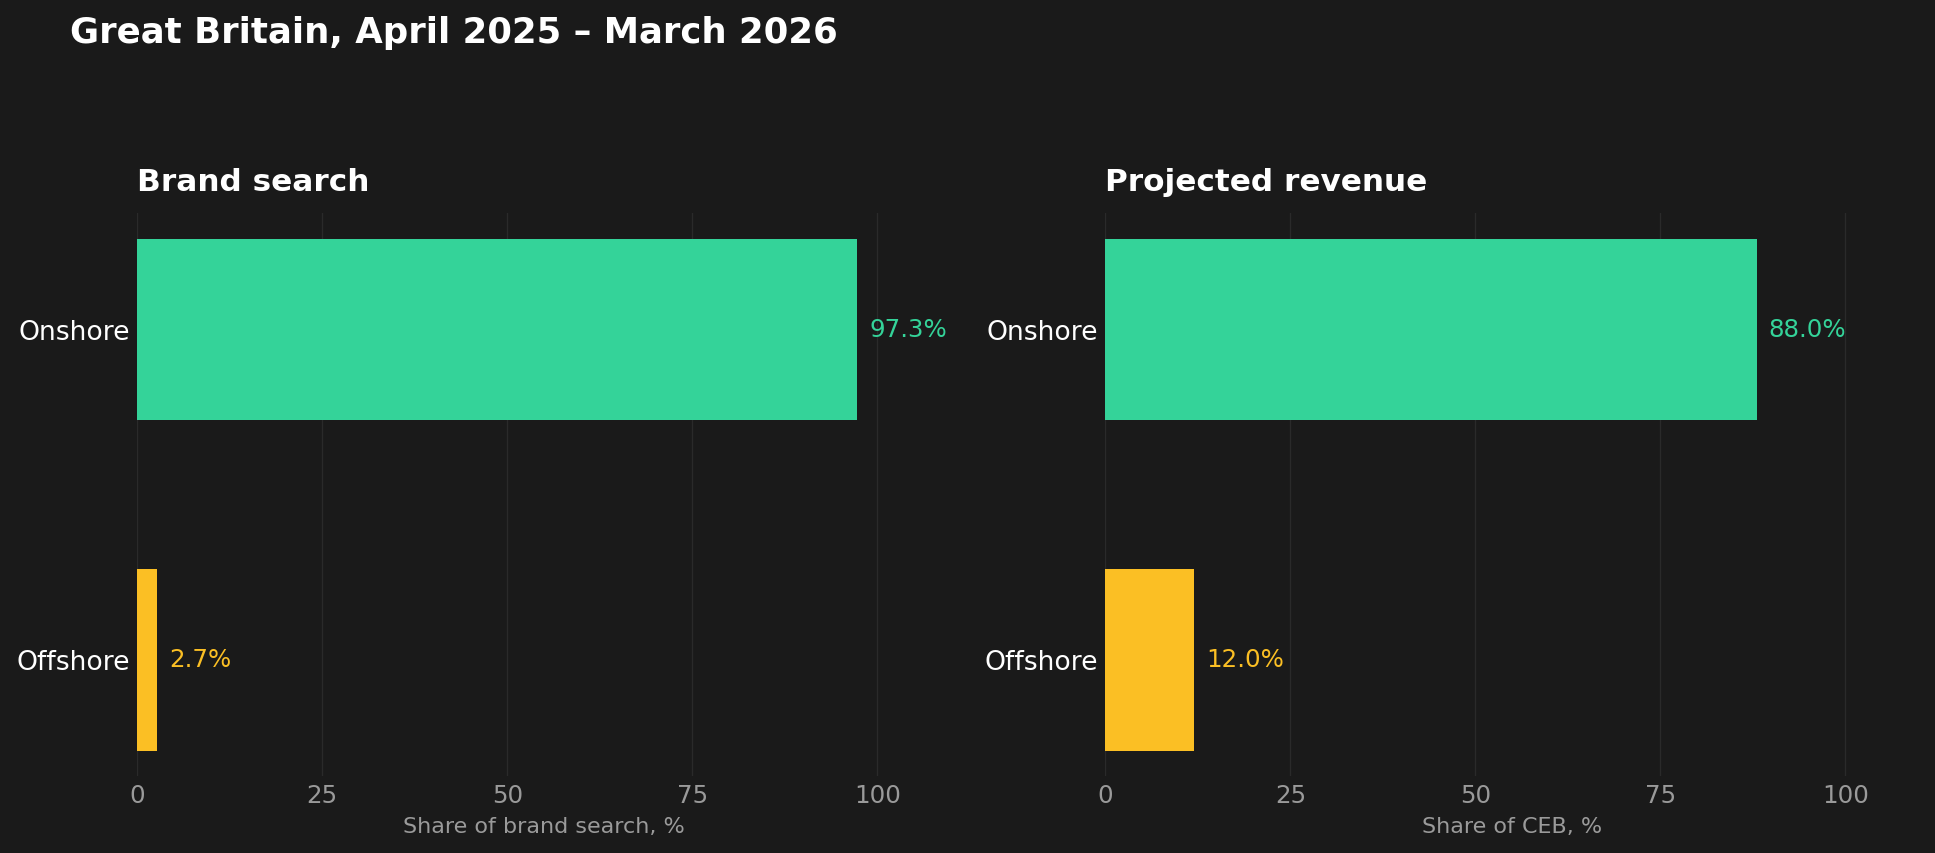
Blask measures the same twelve months with onshore and offshore brands in one frame. The offshore share is small in search and larger in CEB, a gap the GGY tables do not contain.
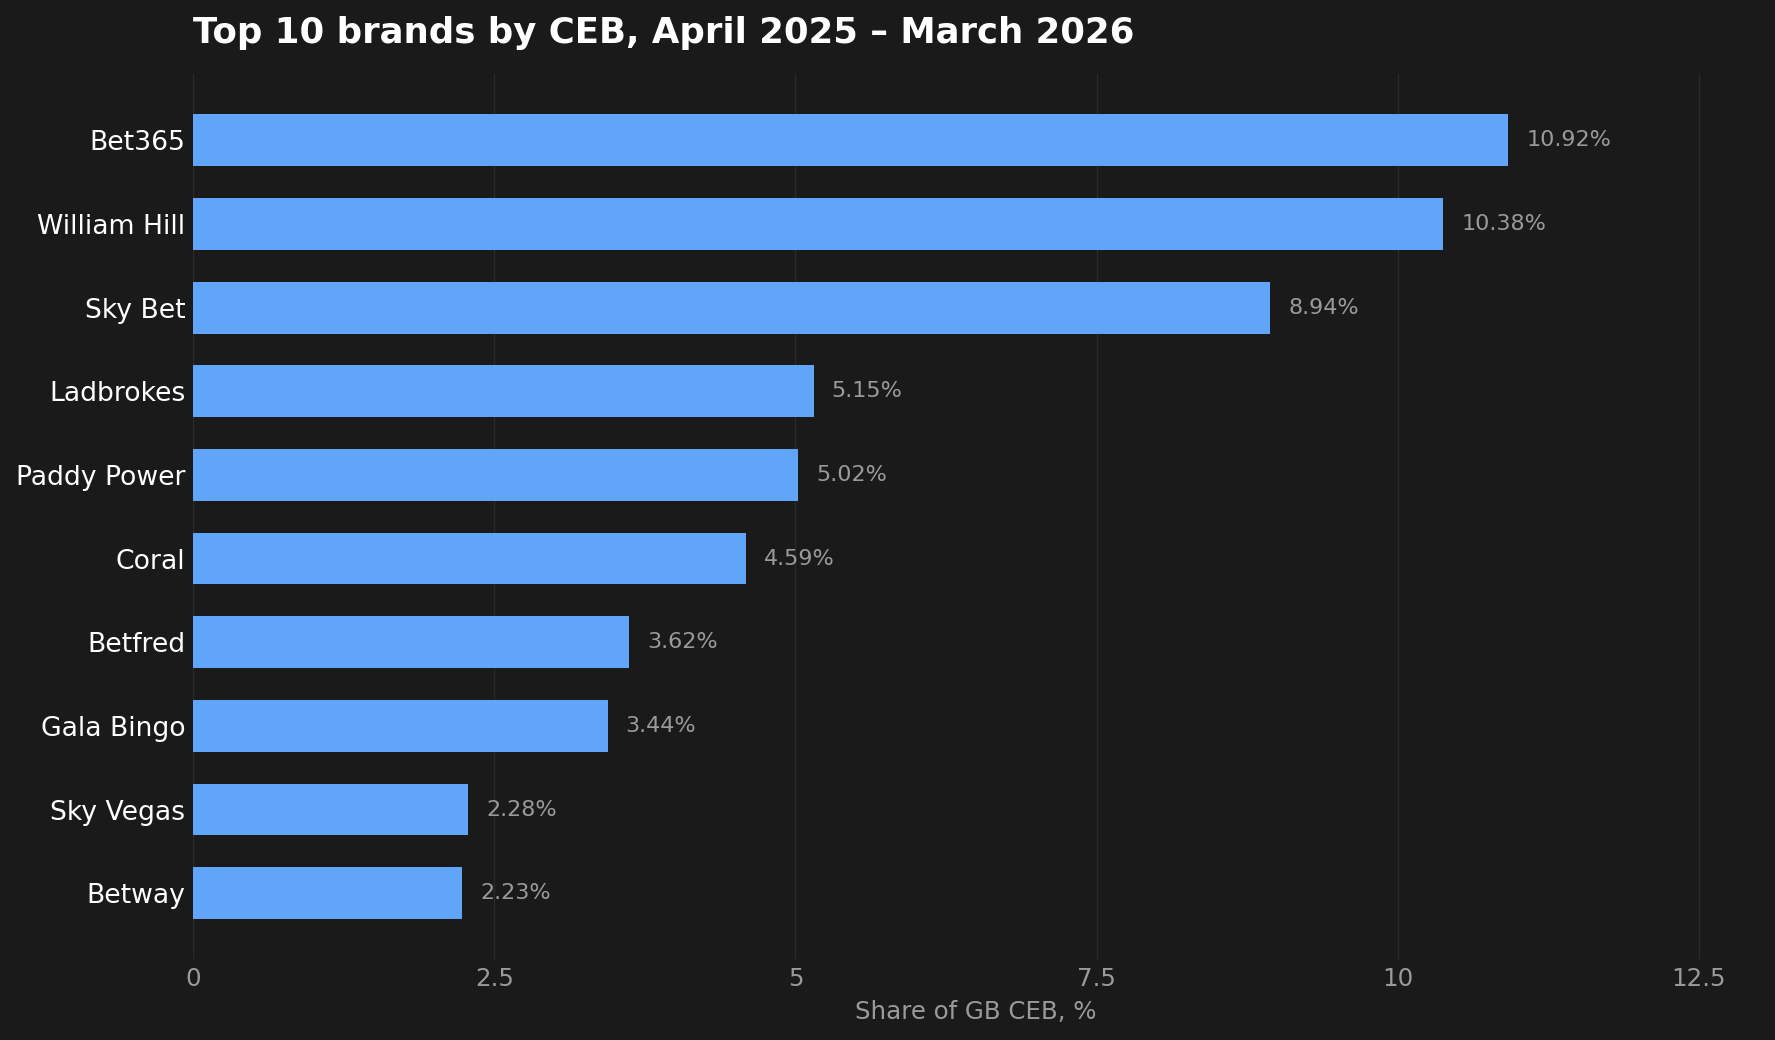
CEB in that window was concentrated in licensed names. The top ten took 56.6% of projected revenue, with Bet365 first and William Hill and Sky Bet behind it. No offshore brand enters that board.
The offshore slice is a long tail. It sits outside this board — the part of GB online demand the annual print cannot see, and the part a higher remote duty will not tax.