
- Updated:
- Published:
Brazil iGaming after the betting ban: demand, brands, and what’s left
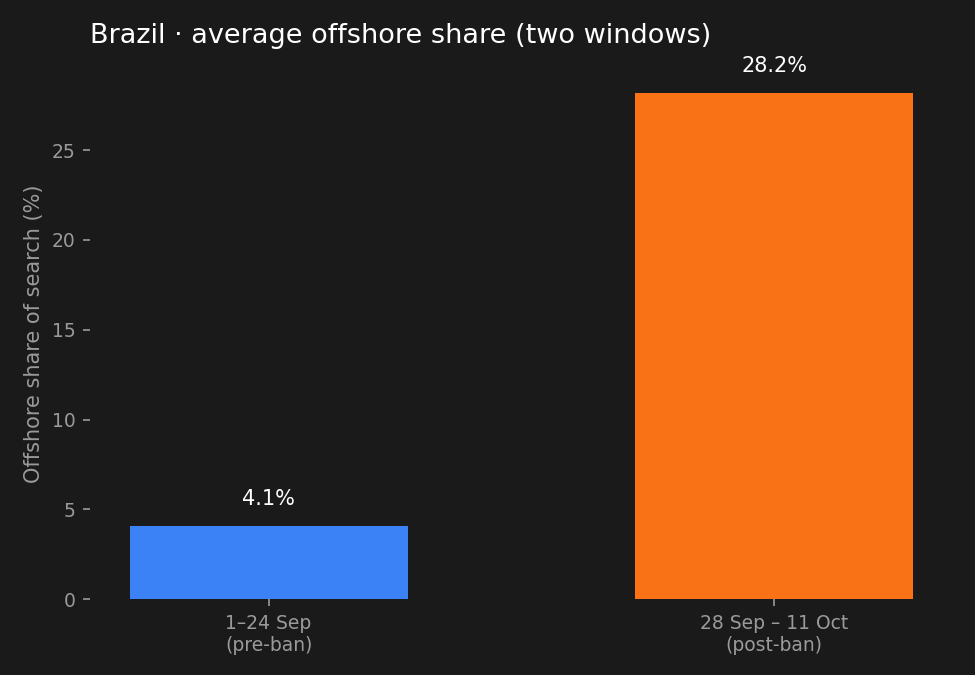
Licensed search demand in Brazil fell 82% in the fortnight after deposits closed, while offshore brands’ share of what remained rose from 4% to 28%.
President Lula’s Provisional Measure 1,394, published on 25 September 2026, stopped new deposits and bets the same day, took authorised sites offline on 6 October, and voids federal licences on 25 October unless Congress converts the measure. Eighteen months after Law 14.790 opened the licensed market, the ban did not erase interest in betting — it removed most measurable search for licensed brands and left a much smaller pool in which offshore names weigh more heavily.
Blask data through 11 October compare two windows: 1–24 September (last full pre-ban stretch) and 28 September – 11 October (after the deposit rule took effect, excluding the volatile 25–27 September spike). The gap between them is the post-ban baseline operators and affiliates are already planning against.
About the data: Blask Index tracks consumer search demand for iGaming brands from Google Keyword Planner and Google Trends. BAP (Brand Accumulated Power) is each brand’s share of that demand. CEB (Competitive Earning Baseline) estimates revenue potential and is shown as a range. Daily licence splits separate onshore and offshore brand demand. Figures are for Brazil; post-ban windows end 11 October 2026 where daily coverage is complete.
Search after MP 1.394
Average daily search in the post-ban window ran 82% below the pre-ban fortnight. Almost all of that move sits in licensed demand: onshore search −86%, while offshore search +15% on a much smaller total. Offshore’s share of the pool rose from 4.1% to 28.2%.
That is not a clean hand-off from licensed books to offshore sites. Index measures brand search; when licensed domains go dark, part of the query volume leaves measurable brand demand for social, creator, and direct channels Blask does not classify as onshore. The offshore share line shows how much of the remaining brand search offshore operators capture — not the full size of the grey market.
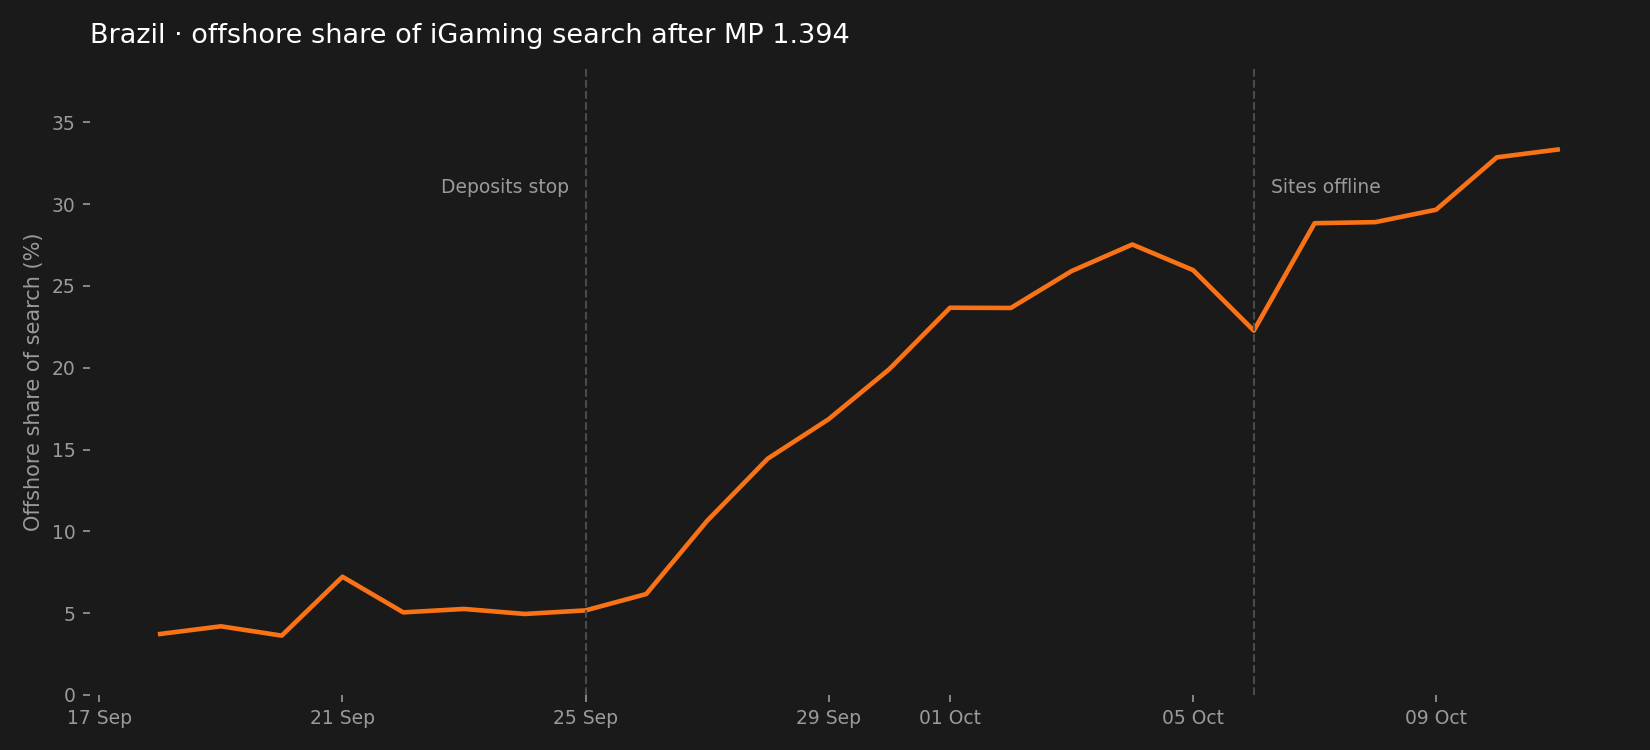
The step-up starts on 25 September and steepens through the first week of October, including the 6 October offline date for authorised sites. By 11 October offshore brands accounted for about one-third of daily brand search in the series.
September’s monthly print still describes a mostly licensed market: twenty-four of thirty days came before the decree. For that month, Blask data attribute 96.7% of CEB to onshore operators ($759M midpoint range $563M–$1.35B for the month) and 3.3% to offshore. That split belongs to the pre-ban licensed book, not to the post-ban fortnight.
The licensed ranking before the ban
Brand rankings frozen at 1–24 September show how concentrated the licensed market had become on the eve of the shutdown. Betano held 33.7% BAP, Bet365 10.2%, Superbet 8.2%, and Sportingbet 6.0%. The top four accounted for 58% of measured demand; 512 brands still posted search in the window.
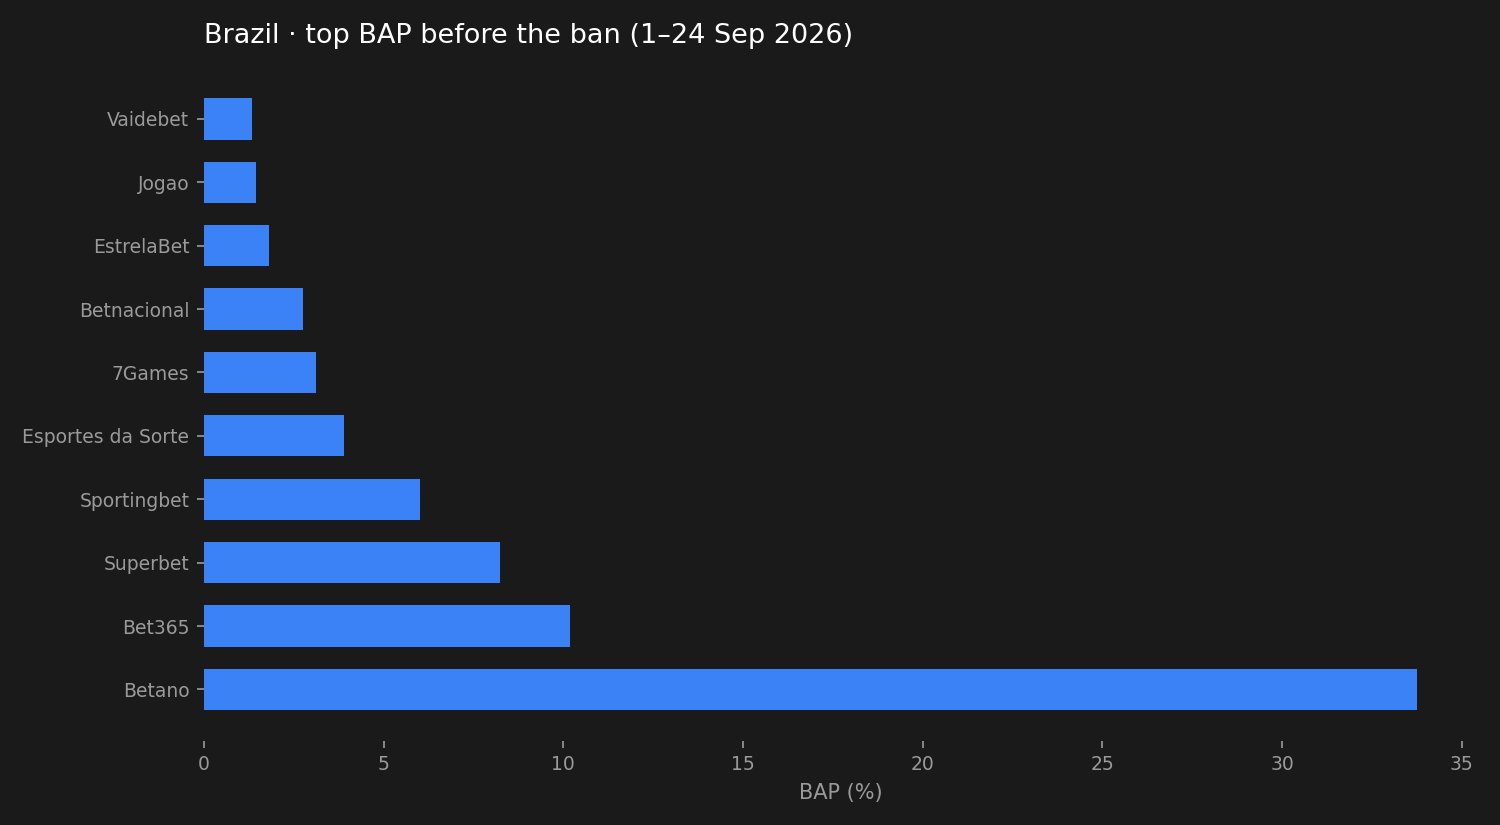
Those shares describe the market Congress and operators argue about when they talk about reopening. They do not describe who captures search today: with onshore demand down 86% in the post-ban window, the licensed leaderboard is a snapshot of what was, not what is still traded in brand search.
For exposure by corporate structure — Brazil-only operators versus multinationals — see Blask’s lost market / lost business breakdown on January–September CEB. The ban hits the same geography for every licence holder; the balance sheet pain depends on how much of each brand sat in Brazil.
Onshore and offshore in the daily series
Licensed and offshore search both jumped on 26 September, then onshore collapsed while offshore retraced to a higher share of a smaller total. The pattern matches the ban note published at the start of October: a short spike when players looked for alternatives, then a structurally smaller market with more weight on offshore brand queries.
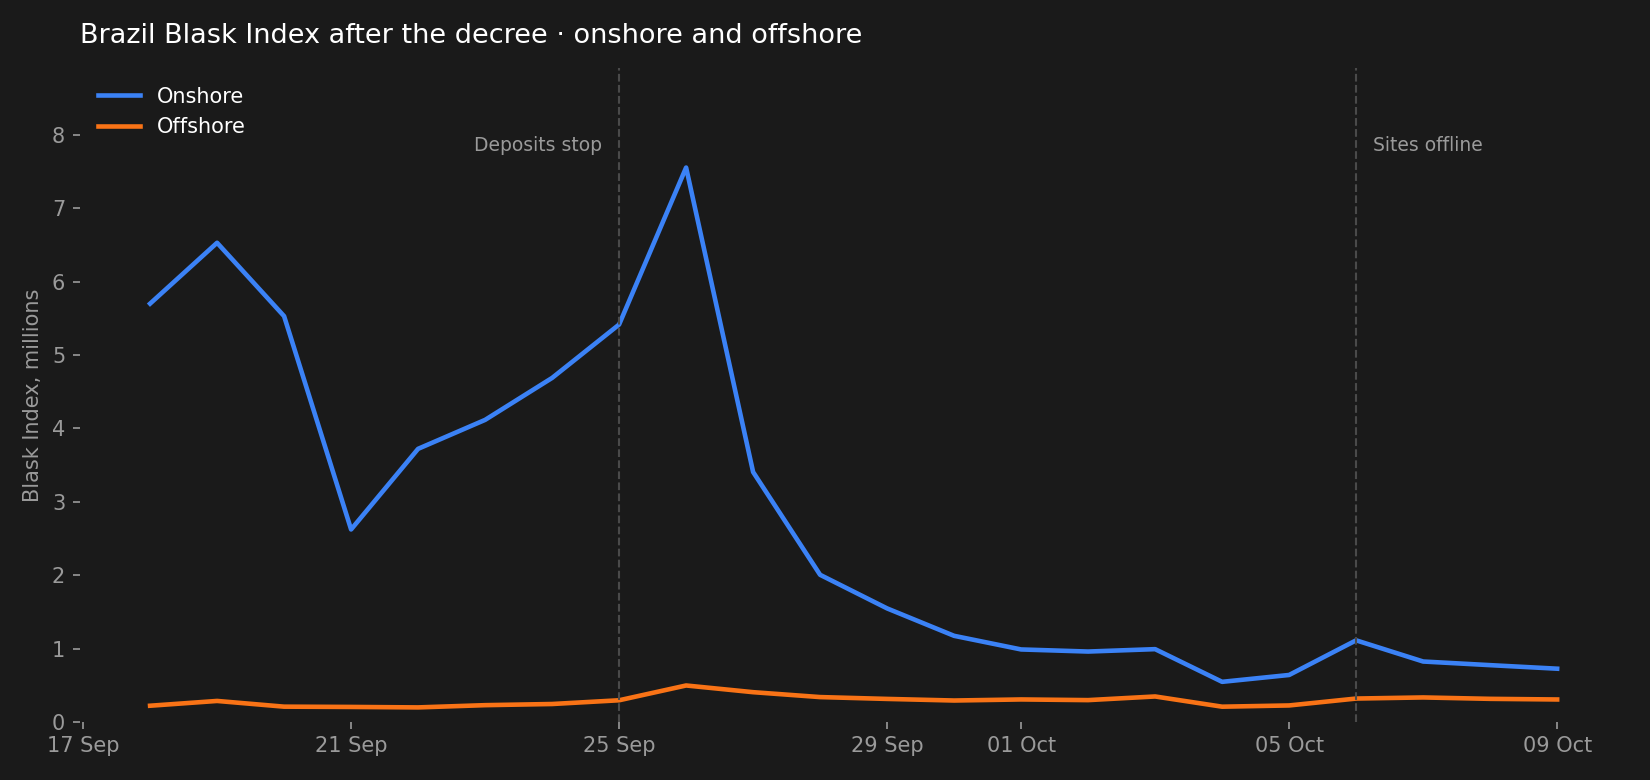
Chart: daily onshore and offshore Index, 18 September – 9 October 2026. Vertical lines: 25 September (deposits) and 6 October (sites offline).
Monthly context: September 2026 finished 2% below September 2022 on Blask Index — the regulated boom’s last month gave back only the gains since 2022, not the climb from 2020. The post-ban fortnight pushed demand well below that September average; Q4 will show the full offline quarter.
What the calendar holds next
Three dates sit ahead of the data:
- 25 October 2026 — authorisations under Law 14.790 expire unless the measure is reversed (Article 4 of MP 1.394).
- 23 November 2026 — first deadline for Congress to vote on the provisional measure, with one 60-day extension still available (Congress).
- Q4 2026 — first full quarter in which licensed sites were offline for most of the period.
Blask will keep the daily licence split and brand panel on Brazil’s market page as Congress and the SPA define whether the licensed book reopens.
Bottom line
Brazil’s iGaming market after the betting ban is smaller in brand search, sharply tilted toward offshore within that remainder, and frozen in brand-share terms at the pre-ban ranking Betano still leads on paper. The open question is not who won Q3 on BAP, but whether licensed demand re-enters Blask’s series at all — and if it does, whether the September concentration around four operators survives the shutdown.
Track Brazil in real time → blask.com/market/brazil