

- Updated:
- Published:
Where one iGaming brand is the market
Twenty markets have a single brand capturing more than three-quarters of iGaming demand. The group runs from local names such as Bet261 and Congo Bet to 1xBet, betPawa, Bet365 and Betway.
Across the 139 countries tracked by Blask from January through August 2026, the typical market was far less concentrated. The median leading brand held 40.6% of national demand, while the highest shares appeared across Africa, Latin America, Asia and one European market.
The analysis uses BAP, or Brand’s Accumulated Power: a brand’s share of total search demand for iGaming brands in a market. BAP measures player attention, not GGR, NGR or operator-reported market share.
The median market leader holds under 40.6% of demand
More markets sit above the halfway line than below the quarter mark. The leading brand captured over 50% of demand in 55 countries, while 33 leaders stayed below 25%.
Leadership across countries remains concentrated among a few international operators. 1xBet ranks first in 19 markets, betPawa in nine and Bet365 in seven. Those counts do not imply the same depth of control: 1xBet crosses 75% in Somalia, Mauritania and Algeria, betPawa does so in Cameroon and Benin, while Bet365 passes the threshold only in Albania.
Bet365 illustrates the range within one brand. Its BAP reaches 87.9% in Albania but falls to 11.6% in the United Kingdom. A global footprint can produce both near-total dominance and a narrow first place, depending on the market.
The concentration ranking adds another lens to Blask’s global ranking of the top iGaming brands in 2026. Global CEB and APS reward scale across markets; the table below isolates the countries where one brand captures almost all measured demand.
Twenty markets pass the 75% threshold
Africa accounts for ten of the 20 markets above 75%. Latin America and the Caribbean contribute five, Asia four and Europe one. The list is broad by operator as well as geography: 16 brands divide the 20 leading positions.
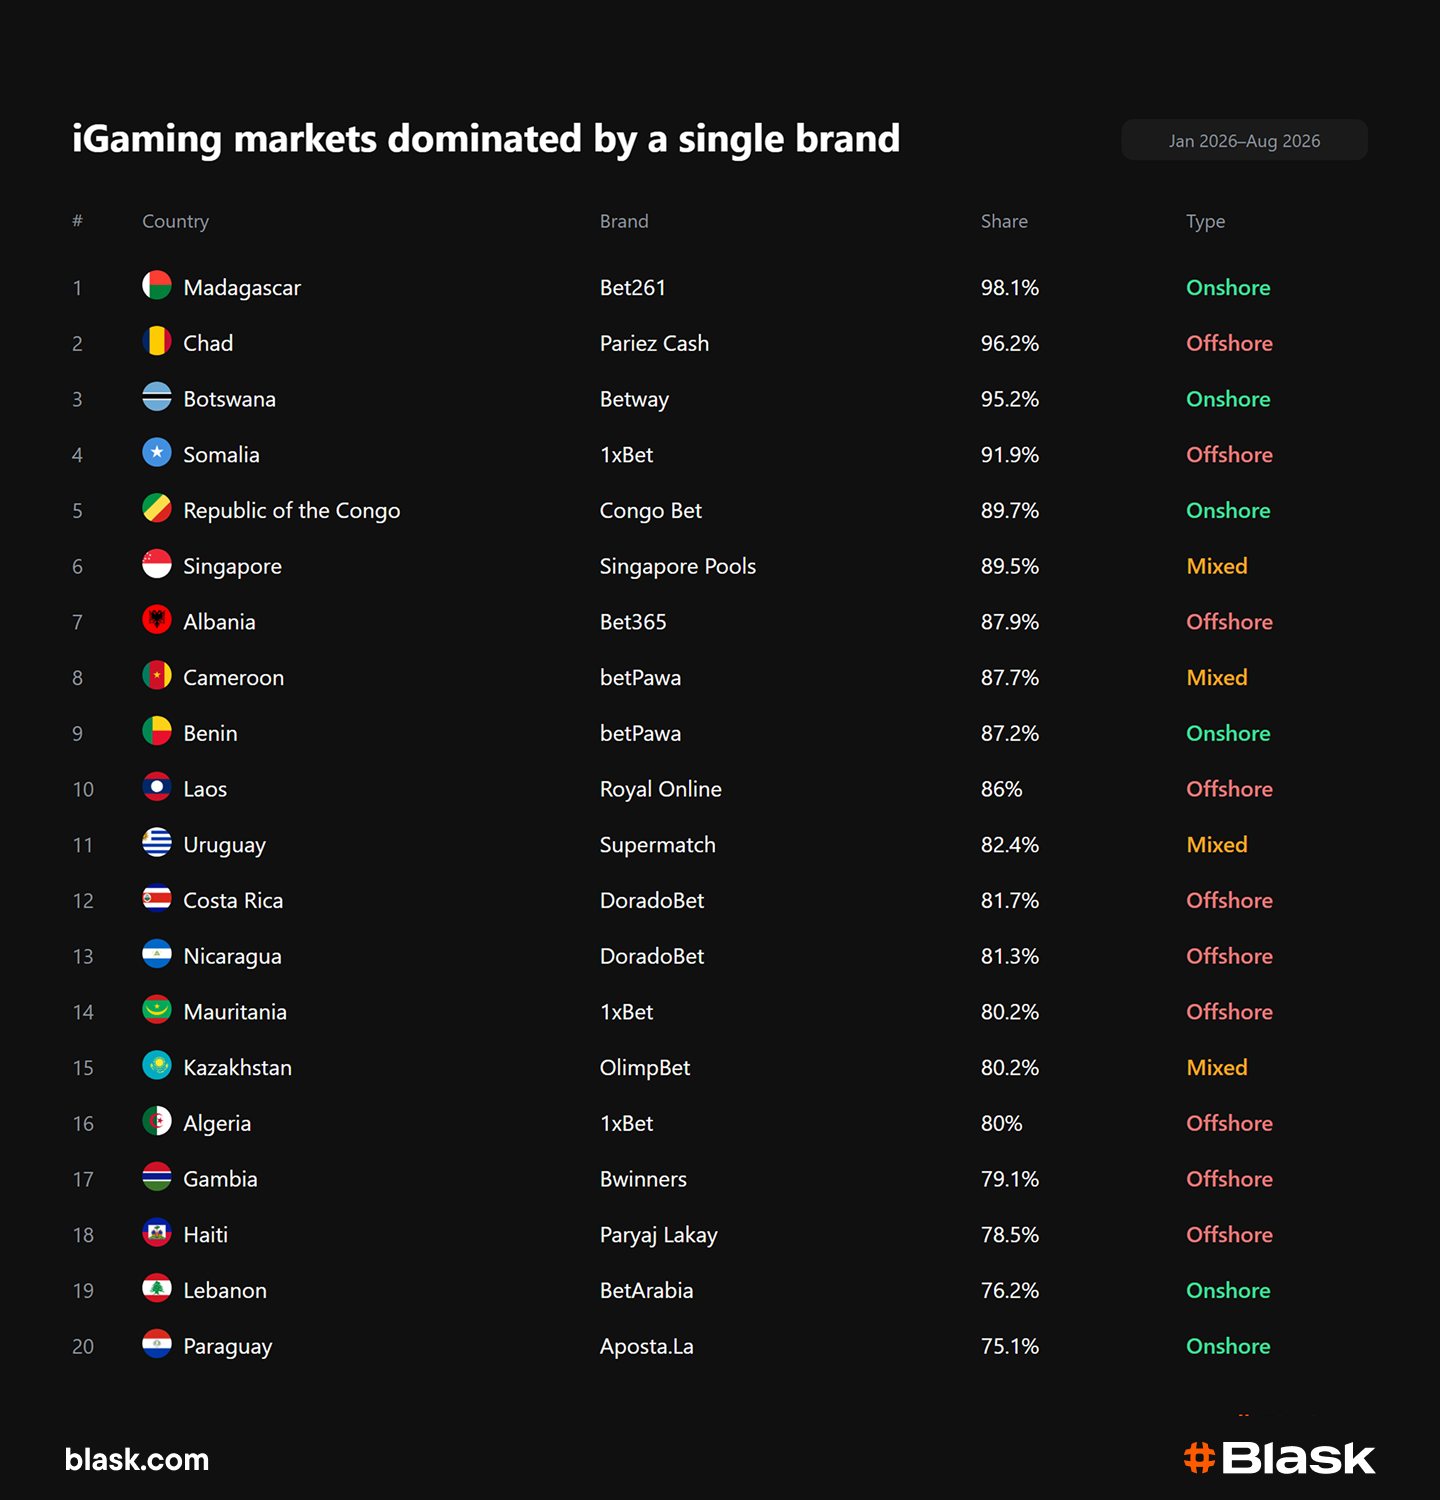
Madagascar, Chad and Botswana form the top tier, each with a leader above 95%. That group contains two locally licensed brands and one offshore operator, so the most concentrated markets do not follow a single licensing pattern.
The lower edge is also tight. Paraguay enters the table at 75.1%, while Ecuador sits outside it at 73.6%. A movement of less than two percentage points would change the membership of the group even if the wider concentration pattern stayed intact.
Locally licensed and offshore leaders split the top group
Licence status separates the full market set more clearly than it separates the most concentrated countries. Across all 139 markets, 52 leaders are Onshore, 30 are Mixed and 57 are Offshore in Blask’s classification. Counting Onshore and Mixed as markets with a locally licensed presence gives an 82-to-57 split over offshore-only leaders.
Above 75%, that advantage disappears. Ten market leaders have a locally licensed presence — six Onshore and four Mixed — while ten are Offshore. Extreme concentration therefore appears on both sides of the licensing divide.
The labels describe the brand’s licence status in that market, not its country of origin. “Local” in this comparison means locally licensed presence. It should not be read as a claim that every Onshore or Mixed leader is a domestic company.
The widest leader is not the most dominant one
1xBet leads more countries than any other brand, but only three of its 19 first places cross 75%. Its strongest position is Somalia at 91.9%, below the leaders in Madagascar, Chad and Botswana.
betPawa’s leadership is narrower and more regionally concentrated. It ranks first in nine markets, with Cameroon and Benin above 75%; its other leading positions range from 70.5% in Uganda to 18.6% in Kuwait.
Bet365 has the broadest spread among the three. Albania sits near the top of the concentration table, Luxembourg reaches 57.0%, and the brand’s remaining first places stay below 50%. Counting first places alone would hide that difference.
Bottom line
iGaming market concentration is extreme within these countries but fragmented across operators: 16 brands divide the 20 positions above 75%, and the licence split is even. The next change to the list is more likely to come from a threshold crossing than from one global operator taking the whole group.
FAQ
Which iGaming markets are winner-take-all?
Using a leader BAP above 75% as the threshold, 20 markets qualify for January–August 2026: Madagascar, Chad, Botswana, Somalia, Republic of the Congo, Singapore, Albania, Cameroon, Benin, Laos, Uruguay, Costa Rica, Nicaragua, Kazakhstan, Mauritania, Algeria, Gambia, Haiti, Lebanon and Paraguay. BAP measures share of search demand, so “winner-take-all” describes attention rather than reported gambling revenue.
Is 1xBet the most concentrated iGaming brand?
No. 1xBet leads the most markets — 19 — but Bet261 has the highest single-market BAP at 98.1% in Madagascar. 1xBet exceeds 75% in three markets: Somalia, Mauritania and Algeria.
How many iGaming markets have one brand above 50%?
Fifty-five of the 139 markets tracked by Blask have a leader above 50% for January–August 2026. The median leader holds 40.6%, showing that a majority position is common but not typical.
Does an Offshore label mean the brand is illegal?
No. In this analysis, Offshore is the licence category attached to the brand-market record in Blask data. It does not make a legal finding about the operator, its users or the jurisdiction.
